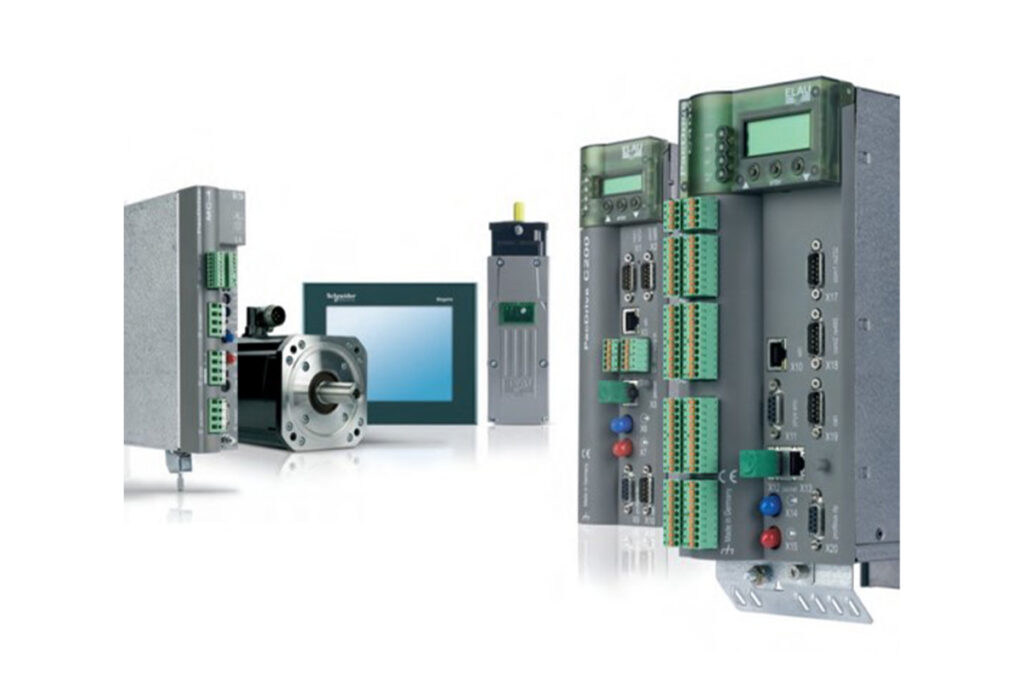
The good news from our recent Customer Survey is that 88% of respondents are aware of PacDrive M obsolescence. The not so good news is 60% operate without any formal mitigation plan. This “readiness-gap” does not necessarily call for a costly system replacement. Rather it highlights an urgent need for a properly defined spare-parts strategy to protect current assets.
The mitigation options available are lifecycle extension, partial upgrade of high-risk components or a full platform upgrade (to e.g. PacDrive 3). However, for most, simply extending the lifecycle for PacDrive M is often the most cost-effective path in the short to medium term for mature sites. If there isn’t a defined deadline for migration/upgrade, the priority must be securing a reliable supply chain for legacy components.
The position the majority of customers find themselves in between high awareness and low commitment would suggest a “hesitation gap”. Despite there being three viable obsolescence mitigation strategies, customers consistently cite the same barriers to acting on any of them.
- Budgetary efficiency: a full system upgrade does require significant capital outlay. However, for most sites, our data shows a comprehensive on-site spares inventory combined with structured support coverage can extend asset life and offer a higher RoI without the disruption of a rebuild.
- Avoidance of operational disruption: the lowest risk strategy for high-output environments is through maintaining the status quo via managed spares and refurbishment.
- Internal skill gaps: as sites often lack the personnel with a thorough understanding of PacDrive M and available options for lifecycle extension, evaluation of any strategy is difficult.
- The run-to-fail fallacy: the only real threat to PacDrive M longevity – certainly in the short to medium term – is complacency. Securing verified legacy spares will allow companies to avoid global secondary market volatility.
- Ambiguity around OEM roadmaps: some customers wait for explicit cut-off points before choosing to act. However, with PacDrive M obsolete since 2018 and the End of Service and Repair Period in 2024, this time has now passed.
Whilst a majority (69%) who have indicated an intention to act have a defined timeline, this still leaves a significant number showing awareness but without a plan. This leaves them potentially at risk and a narrowing of the window for a controlled transition.
As PacDrive M hardware becomes more difficult to source, the case for a specialist spares partner becomes stronger. However, whilst the principal focus has been on PacDrive M obsolescence, it should also be noted that even though PacDrive 3 is not obsolete, lead times can sometimes be long. Proactive stock management is therefore important across both platforms.
Overall, we found the most resilient companies were not the ones in a rush to migrate; rather they are those who had secured their legacy supply chain. Treating PacDrive M as a long-term asset and backed by specialist support can avoid the significant costs of premature platform replacement.